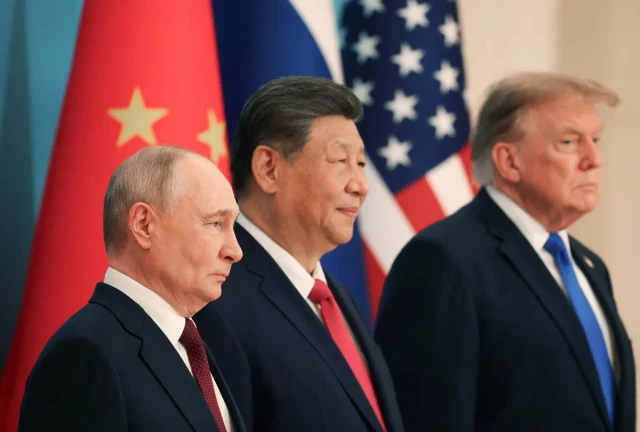
On 19 November a photograph was taken in Shenzhen. Trump, Xi and Putin in the same frame. A ninety-minute meeting, a four-point "peace declaration", plenty of smiles. Trump told the Chinese leader "you are my friend". The world's press called the picture historic. Some of my readers put a fair question to me: for years you have been writing that these wars are run from a single centre for a single purpose. If the three great powers sit at one table and talk of peace, what becomes of your thesis? My yardstick in this piece is set from the start: look at the shipping, not the photographs.
The question is a fair one. But the thesis must first be stated correctly, because the reader has made it a little heavier than it is. What I argue is that Washington uses the energy and financial consequences of these conflicts to preserve its own primacy. That does not mean it collects all the gains or controls every development. I drew the same distinction in my book: the existence of a strategy does not require every development to have been directed from a single centre and without error. Benefiting from an event, starting it and steering its entire course are three separate claims. My thesis asserts the first with confidence, the second in part and the third not at all. So let me first recall what I said, and then set it against the summit.
What had I said?
On 27 February 2022, the third day of the war, I published in this column a piece titled "The Montreux Convention... Questions... and the Bear Trap Putin Fell Into". I wrote that Russia's attack was a clear violation of international law, and I stand by that today. I also wrote this: as the Normandy Format edged towards peace, the United States and Britain stayed away from the table, Zelensky was encouraged while it was announced that NATO would not fight, and Putin walked into that contradiction. As the winners I named the US-UK bloc, which was binding Europe to itself in security and energy, and the energy exporters, shale producers included. The losers were Ukraine and Russia, and Turkey's shield was Article 19 of Montreux. When the Iran war began in the spring of 2026 I widened the thesis. In "Is the United States Losing Its Status as a Hegemonic Power?" I described aircraft carriers as the floating guarantors of the dollar, used the concept of the "Weapon-Dollar coalition" and read Iran's announcement that it would collect Hormuz transit fees in yuan as a de facto declaration of the petrodollar system's collapse. In "The Bankruptcy of the Paradigm" I described how cheap drones had left expensive platforms helpless.
In the television programmes I joined with Gürkan Zengin I said the blockade had been imposed not to open the strait but to keep it closed, and I called this "controlled closure". I counted three levers: an oil price that keeps energy expensive for China and Europe, a permanent military presence in the Gulf, and the petrodollar. I added that Russia, locked into Ukraine, could not make free use of the high price. I interpreted the "reset" in the "world's most powerful reset" that Trump posted on 10 April not as a return to zero but as a repositioning of the powers in the world order, and I said that this shift was running through the sea passages. In "Saving Private Dollar", published in SeaNews in October, I tied the pieces into a single picture: Hormuz sets the price, Bab el-Mandeb lengthens the route, the Black Sea neutralises the rival, the common product of all three is fear, and fear drives the world into the dollar. In the fourth edition of my book "The Eastern Mediterranean Question", published these days, I treated the Ukraine war, the Gulf war, the closure of Hormuz and the petrodollar as squares on the same board. That is the thesis. Now to the summit.
What happened in Shenzhen, and what did not?
The trilateral declaration consists of four points: reform of the United Nations, increasing the production and supply of refined petroleum products, the International Criminal Court not abusing its jurisdiction and respect for the immunity of state officials, and dialogue on reducing nuclear risks. What is absent from the declaration is more instructive. No Iran, no Hormuz, no Ukraine, no dollar, no sanctions, no frozen Russian assets. In the bilateral meeting between Trump and Xi the trade truce that expires on 10 January was not extended. Three days before the summit Washington had widened its export controls on chips. The rare earths bottleneck continues, Taiwan is unresolved. Trump said the two countries had "a very strong commitment" to "the smooth supply of energy through the Strait of Hormuz" and to "preventing Iran from possessing nuclear weapons". No commitment from the Chinese side was recorded. Speaking to Fox the same day, Trump praised the blockade as "the most effective thing we've done", called the Islamabad memorandum he had himself signed at Versailles five months earlier "a waste of time", and said of Iran "we'll finish it off soon".
Nor did the guns fall silent at sea during the summit. On 16 November the BETUL 8, with eight Turkish seafarers aboard, capsized off Bulgaria after a sea drone attack. The next day, in the same area, the GAS HUSKY, carrying 3,400 tonnes of LPG, sank after four hits, and 19 Filipino seafarers were rescued by helicopter. The LARISSA 1, struck off Romania, was brought to İnebolu for repairs. On the evening of 17 November, off Khasab in the Strait of Hormuz, ADNOC's tanker NAVIG8 MESSI was hit: 11 injured, one missing. The number of confirmed attacks in and around Hormuz in November rose to 18. On 18 November Iran struck Bahrain and Kuwait for the first time in two months. Ukraine hit the Crimea bridge three nights in a row. Debris from a Houthi missile aimed at Riyadh fell on the Public Investment Fund tower. While the leaders smiled, ships were burning on all three fronts.
Does it refute the thesis?
The thesis has a single rule: the photograph changes, the money tap is not touched. Let us test the summit against that rule.
In Hormuz, the blockade did not make it into the joint text. All China took from the summit for the strait was a sentence. No timetable, no mechanism. On the Russian front Putin came in from the cold. He had his photograph taken and carried the emphasis on the immunity of state officials into the declaration. That gain is political, not financial. No easing of sanctions, the frozen 300 billion dollars stays where it is, and Ukraine does not appear in the declaration with a single word. The first half of the formula "it will not collapse, but it will not win" is working. The second half, as I will show below, is being tested by the data. On the Chinese front there was no concession on chips, rare earths or tariffs. On the dollar front, three great powers sat at one table and never mentioned the currency.
In 2022 I wrote that Europe would be condemned to US-UK leadership. Europe's absence from this summit strengthens my concern that the continent's diplomatic weight is weakening. That is an observation, not a confirmation. The continent is outside the room in talks that directly concern its security, and it is not invited to the table where the war on its own soil is discussed.
The real challenge the summit poses to my thesis is not the friendly photograph either. That the three powers took a common position on UN reform and on the immunity of state officials shows that great powers with conflicting interests can act together in certain areas. To dismiss this as nothing more than a prestige gain for Putin would be too easy. What was agreed is not a peace order but a joint search for political protection against international courts, and the UN reform clause says nothing about the direction of reform. Even so, the ability of three powers to take a common stand in one area does not fit neatly with the "exploiting conflict" logic of my thesis. There is also a simpler explanation: great power diplomacy cannot settle these wars over a lunch. The photograph did not falsify the thesis, and by itself it does not prove it.
There appears to be a tension between my own writings as well. In April I read Iran's announcement that it would collect transit fees in yuan as a de facto declaration of the petrodollar's collapse. Today I am writing that the same process has lifted the dollar. The two pieces measure different indicators. The April judgment concerned the norm in the payment system and military deterrence, today's finding concerns the exchange rate and the reserve share. To put it more narrowly today: the bond between the dollar and oil has not dissolved, but it has been visibly strained. Deterrence, weight in payment systems, reserve share and exchange rate are separate indicators, and today they point in different directions. Erosion of military deterrence does not end financial primacy by itself, and a rising exchange rate does not close the crack in the payment system. What I wrote in "The Bankruptcy of the Paradigm" applies here too: with actors able to impose costs on great powers using cheap drones, how "controlled" Washington can keep the closure is an open question. The bill for the cost of living that voters handed down in November suggests the limits of control may already have been exceeded.
Three more points strain the thesis. The first is the refined products clause and sanctions. The three countries pledged to increase the supply of refined petroleum products. I count the high oil price as one of Washington's levers. This clause shows that the lever has a domestic ceiling. Washington has felt that ceiling before. Ten days after Hormuz closed, on 12 March, OFAC issued a temporary licence allowing Russian oil already loaded on ships to be sold until 11 April, and suspended its own price cap for those cargoes. It was temporary and limited to cargoes on the water. But if such licences turn into a permanent exemption covering new loadings, the "containing Russia" leg of the thesis weakens.
The second is Russia's revenue. The sentence "Russia cannot profit from expensive oil" cannot be said as it stands in the face of the October data. According to CREA, Russia's crude export revenue rose to 449 million euros a day in October, the highest since June 2022. The monthly average for Urals, at 101.7 dollars, is the peak of the organisation's series, which begins in October 2021. CREA estimates that high oil and gas prices in the six months since the strikes on Iran have brought Russia roughly 36 billion dollars in additional export revenue. In my book I had put it more carefully: Russia benefited, but could not use this opportunity as freely as Western producers. That is the correct sentence. A discount of 23 dollars a barrel, the cost of the sanctioned shadow tankers that carried 60 percent of its seaborne oil in October, frozen reserves and revenue flowing into the war give the word "freely" its content. But deprivation is one thing, constraint another. If revenue stays at this level I will have to revisit the word "containment".
The third is the trilateral format. Britain was not at the table. Yet in my writings I spoke of "US and British leadership". My answer is this: the City's place is not the summit table but the plumbing. That is not a metaphor, it is a mechanism. The G7 price cap is enforced through London-based P&I clubs and the Lloyd's war risk market. Britain has sanctioned hundreds of shadow fleet vessels and announced this year that it would begin stopping shadow fleet tankers in its own waters. The cameras show Washington, they do not show the vault. Still, I must concede this: these mechanisms prove the weight of the financial infrastructure, not that the British state runs the wars.
Staged friendships
The part of the summit that really needs reading is not the embraces but their record. Trump has staged this choreography with Iran many times. Three examples will do. In June 2025 he said "I'll decide within two weeks", and a few days later Fordow was struck. In February 2026, with indirect talks under way in Oman and a technical meeting scheduled in Vienna, the bombs fell on the negotiating table on 28 February. On 17 June he signed a memorandum at Versailles, on 14 July he brought the blockade back, and on 19 November he declared the same memorandum "a waste of time". In the months between, the cycle repeated in the same order: a deal announced, a ceasefire, a blockade, a new memorandum, a cancelled signing, a rejected offer, and a tanker struck the day after the words "the war is essentially over".
The same choreography was applied to Putin. In August 2025 the red carpet was rolled out in Alaska, and two months later Rosneft and Lukoil went onto the sanctions list. The declaration that emerged from the table of the Putin who was called "my friend" in Shenzhen did not contain the word Ukraine. In the week Xi was told "you are my friend", chip controls were widened. In this theatre the embrace is the interval. When the curtain rises, the play is the same play. So to look at the Shenzhen photograph and say "the three powers have agreed" is about as accurate as looking at the Versailles photograph and saying "the war is over". Five months have passed since that photograph.
The months ahead, if the thesis holds
If the present balance of interests continues, this is what I expect. The trade truce will be extended at the last minute, at the G20 in Florida in December or by 10 January, because tariffs are bargaining material, not the core of the thesis. In Hormuz I do not expect the blockade to be lifted through a comprehensive settlement. Trump's "we'll finish it off soon" keeps the possibility of a new operation on the agenda, but by itself it does not signal a decision to strike. When the strait does open, I expect it to open within a framework that makes the American naval presence and the transit regime permanent. In the Black Sea I expect the attacks to continue and the CPC exception to be preserved. In the CPC case what matters for sanctions is the origin of the cargo. Oil documented as Kazakh in origin is kept outside the American import ban on Russian oil, and the line carries Russian oil as well. According to a report the FT based on officials, Ukraine agreed not to target CPC infrastructure or non-Russian vessels that meet certain conditions. At Bab el-Mandeb, Saudi Arabia remains where it was left, alone. On the dollar, the IMF reserve data due at the end of December and central bank gold purchases should be watched. The fate of the refined products clause should be watched too. Non-implementation, however, would not strengthen the thesis by itself, since it could stem from capacity problems, disagreement or reluctance. If it is applied as a permanent exemption for Russian products, the thesis takes a hit.
Fear ran to the dollar and gold fell: will it last?
The numbers are in front of us. Gold, which set a record of 5,627 dollars in January, fell below 3,900 dollars in mid-November, its lowest in thirteen months. The dollar index is at a nineteen-month high. The yield on the ten-year US Treasury is above 5 percent. Inflation fed by the oil shock has pushed producer prices up 6.5 percent, and the market treats a Fed rate rise in December as almost certain. The chain was built like this: war lifted oil, oil lifted inflation, inflation lifted interest rates, and interest rates lifted the dollar. Fear fed the dollar by two routes, as a haven and as a yield. This is exactly what I called "the elevated dollar" in "Saving Private Dollar", and Russia, unable to use freely its sanctioned reserves and the cash flows tied to them, is left outside that return.
Will it last? Anyone who wants to speak with certainty here will be wrong. In the autumn of 2008 and in March 2020 too, fear ran first to dollar cash, gold was sold, and months later gold set new records. This time there is a different element: the dollar is rising together with yields, and the Fed is preparing to raise rates in the middle of a war. As long as oil stays expensive and the Fed stays tight, the pressure on non-yielding gold may continue. On the other side of the coin are the central banks that kept buying as the price fell. Gold lost 16 percent in the second quarter, and in the same quarter official purchases of 289 tonnes set a record for second quarters. In the short run funds set the price, while ownership shifts to central banks. Moreover a Treasury yield above 5 percent is as much a burden for Washington as an achievement: the interest on 40 trillion of debt grows every quarter. After a while the strong dollar may cease to be the solution and become the problem itself.
So the answer hangs on three unknowns. How much longer the war and the blockade will last. How much longer the Fed can carry high rates under this debt load. Whether Washington will use the dollar as a weapon once more, or preserve its role as a haven. Whether the same currency can be both weapon and haven for long, that is the real question. It cannot be known today. The one thing we do know is that at either end of this uncertainty the bill is sent to the same addresses.
Testing my predictions
A thesis that cannot be falsified is not a thesis but a belief. The indicators below will test my predictions that the present order of interests will continue in the months ahead. A change of policy in 2027 would not erase the finding that Washington profited from these conflicts in 2026, but it would weaken the forward-looking claims of the thesis.
First, Hormuz. If the blockade is lifted before the end of the first quarter of 2027 and the strait opens on a timetable within a framework that neither entrenches the existing American military presence nor leaves control of transit to Washington, my prediction that the opening will be tied to a permanent American gain in control weakens. Second, Russia. If within the same period a general licence covering new loadings of Russian crude and products is issued, the price cap is lifted or the main body of assets held at Euroclear is released, my prediction that Russia will be kept under constraint falls. Third, the dollar. No single number refutes the thesis here, because the reserve share also moves with exchange rates and asset prices. Still, I set a monitoring threshold. If the dollar's share of reserves in the IMF data falls below 55 percent by the end of 2027 and stays there, that is below the lowest level the series has recorded to date, and it weakens my expectation that the dollar will keep its weight in official foreign exchange reserves. Washington failing to respond while Gulf exporters' non-dollar sales grow would point the same way. Fourth, the Black Sea. If by mid-2027 an arrangement is established that actually stops attacks on merchant ships, my prediction that the attacks will continue will have proved wrong. If any one of these comes about, I will be the first to write it in this column. None of it happened in Shenzhen.
The fourth gate
I return to my yardstick. Look at the shipping, not the photographs. There were eight Turkish seafarers on the BETUL 8. The LARISSA 1 came to İnebolu for repairs. In the last six weeks seven ships were hit in Bulgarian waters alone. The European Union is setting aside 50 million euros for a Black Sea Maritime Security Centre to be established in Bulgaria and Romania. If that architecture is built without Turkey, the country with the longest Black Sea coastline becomes a spectator in its own sea. Three gates are burning. The fourth gate is the Turkish Straits, and for ninety years Montreux has kept these waters out of the fire.
My answer to the question of what we should expect from the trilateral summit is this. Shenzhen did not show that the order of interests I describe has changed. Nor did it prove that the wars are run from a single centre. Consistency is not confirmation. In the months ahead my thesis will be tested by concrete changes in sea passages, sanctions and energy revenues. Turkey has three tasks. To apply Montreux with resolve. To strengthen the safety of commercial navigation in the Black Sea. To take part in shaping the regional security order now being built, from inside rather than from the sidelines. In April I said that Turkey's long-term place lies within the European security system. The EU's Black Sea initiative is the first test of that view. Holding the gate means protecting Montreux while leading the cooperation that will secure the safety of commercial navigation in the Black Sea.