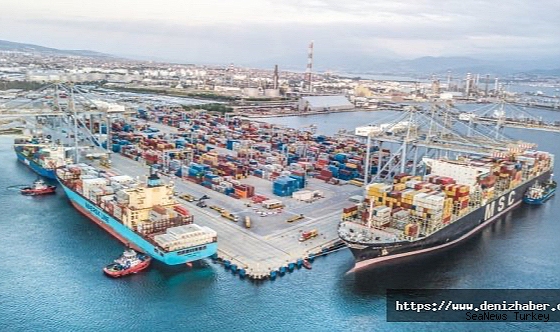
Global container shipments hit a record 17.46 million TEU in August, with freight rates at a two-year high, signaling robust trade growth.
The latest data from Container Trade Statistics (CTS) confirms that global container shipments reached a historic high of 17.46 million TEU in August, with freight rates climbing to their highest level in more than two years. For the first eight months of 2026, cumulative global container throughput reached 133 million TEU, representing year-on-year growth of 4.7%.
CTS reports that August global container shipments surpassed the record set just one month prior in July, advancing 3.7% compared to August 2025. Global container trade sustained its growth trajectory despite a range of persistent adverse conditions, including rising fuel costs, restricted transit through the Strait of Hormuz, Panama Canal limitations, and shifting tariff conditions. August volumes registered 7.2% above the same period in 2024 and 12.9% above August 2023 levels.
According to CTS data, the global price index reached 117 points in August - its highest reading since July 2024 - standing approximately 50% above January 2026 levels and 44% above August 2025 levels. CTS attributes the rise in the freight rate index to pricing pressure that has accumulated steadily since late February. Vessel diversions on major trade lanes have disrupted operational continuity, constraining available capacity and elevating operating costs, with both factors exerting upward pressure on rates.
North American container import volumes registered 2% growth year-on-year through August, extending the gradual recovery trajectory that has been in place since May 2026. Increased exports from Asia have supported this recovery, with trans-Pacific trade volumes recording cumulative growth of 5% for the year to date. Sub-Saharan Africa posted the highest import growth rate of any region, advancing 13% through August.
The Indian Subcontinent and Middle East region stands as the sole market to record both import and export declines: imports have fallen 5% year to date, while exports have contracted 10%, representing a reduction of nearly one million TEU against the first eight months of 2025.
Asian exports have expanded 8% year to date, adding approximately 6.3 million TEU relative to the same period in 2025. European exports, which declined in the opening months of the year, have since recovered to broadly flat levels. CTS attributes this improvement to stabilizing or increasing cargo flows across the majority of destination markets.
Despite August's record-breaking shipment volumes, CTS cautions that a deceleration in month-on-month growth may signal softening demand, identifying volume performance and freight rate trajectory as the defining questions for the final quarter of 2026.


