Freight rates diverge as European routes rebound while U.S. rates ease, influenced by capacity adjustments and market dynamics.
Freight rates on European and American shipping lanes are showing contrasting trends. On October 16, the Shanghai Export Container Freight Index (SCFI) rose to 3,679.58 points, a modest 0.42% increase, marking the second consecutive week of gains. Rates on European, Mediterranean, and Central/South American West Coast lanes saw increases, while U.S. West Coast and East Coast rates recorded slight declines.
Several factors are driving these changes, including carrier rate pushes, capacity adjustments, improved port conditions, and the gradual resumption of Red Sea routing. Freight forwarders face varying rate conditions across lanes, with prices influenced by specific carrier policies, available space, and timing.
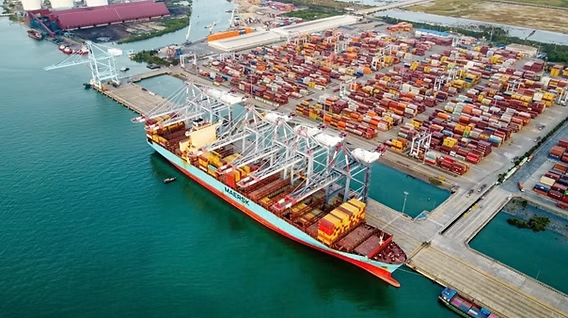
U.S. freight rates saw slight declines, with West Coast rates dropping 0.78% and East Coast rates falling 1.13%, driven by additional vessel capacity and eased Panama Canal restrictions. However, year-end demand for pre-Christmas inventory replenishment is providing underlying support. Rates to the U.S. West Coast and East Coast remain elevated, at around $8,250 and $11,000 per 40-foot container, respectively. These figures vary based on carrier, contract terms, and booking timing. Near-term rates are expected to stay relatively high as capacity additions continue to balance out demand.
European and Mediterranean lanes saw stronger rate increases, with rates rising 2.66% and 8.1%, respectively. Carriers plan further increases from October 19, with adjustments ranging from $800 to $1,500 per container. However, weak demand and rising capacity could limit the success of these rate hikes. Market transaction prices have climbed from $3,000-$3,400 to $3,800-$4,800 for some lanes, but rates remain influenced by carrier strategies, shipment timing, and negotiation leverage.
The gradual resumption of Red Sea transit routes is reducing Asia-Europe transit times by 10-14 days, improving efficiency and raising capacity. While promising, risks like security concerns and insurance costs persist. Two blank sailings on European lanes and six on U.S. lanes are planned for the coming week, reflecting incremental capacity shifts.
Key developments to watch include the execution of European rate hikes, space availability on U.S. trades, and how the Red Sea resumption impacts Asia-Europe capacity and rates. The market's focus remains on whether rate increases can hold through actual transactions amid fluctuating supply and demand.