
Freight rates show mixed trends post-Golden Week, with trans-Pacific routes steady while Asia-Europe faces significant struggles.
The container shipping market has entered a period of stabilization following China's Golden Week. The Shanghai Containerized Freight Index (SCFI) rose marginally by 0.05%, breaking a two-week decline. However, while Europe and Mediterranean routes showed signs of recovery, trans-Pacific lanes to the US West and East Coasts remained steady but face correction pressures. The limited rise in the SCFI is not yet indicative of a sustained upward trend, with near-term rates influenced by demand fluctuations and capacity management.
On trans-Pacific routes, rates remain relatively high but may enter a correction phase. The Shanghai-Los Angeles route declined 3% to $7,624 per FEU, while Shanghai-New York dropped 2% to $10,220, according to Drewry's World Container Index. Despite these declines, fewer planned blank sailings—falling from 11 to 4—could maintain short-term rate support if demand holds steady. However, increased capacity from fewer blank sailings may lead to downward pressure on rates if demand does not pick up. A buffer period in US-China trade tensions could provide some support, though it is unlikely to overturn seasonal softening trends.
In contrast, Asia-Europe routes face more pronounced rate challenges. Carriers aim to implement a $1,500 per FEU general rate increase on October 15, but whether this will succeed remains uncertain. Some rates on these lanes have already fallen below $3,000 per FEU, with weaker transaction prices persisting. Demand in Europe has not deteriorated significantly, with recent volumes outperforming expectations. However, the resumption of Red Sea and Suez Canal transits could release capacity and push rates lower. Security risks in the Red Sea and operational challenges at key hubs like Singapore may further complicate capacity adjustments.
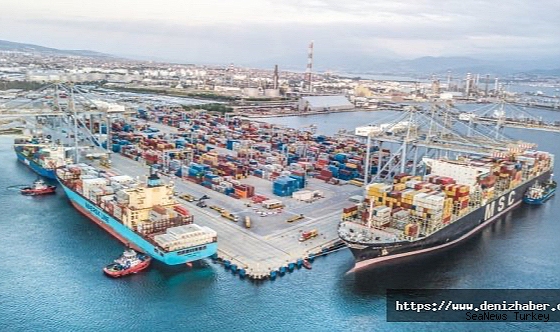
Port congestion remains a critical factor, with delays at major ports like Shanghai and Ningbo halving post-Golden Week. Reduced waiting times may improve turnaround but could also raise effective capacity, influencing rate levels further.
Overall, the container market remains divided. Trans-Pacific routes show resilience but face potential corrections, while Asia-Europe lanes struggle to stabilize. Key variables like supply-demand dynamics, capacity adjustments, and cargo volumes will determine whether current trends signal a lasting recovery or a temporary pause in a broader downturn.